
Canada’s tax system needs an overhaul. In this series, The Globe and Mail explores the bold policy choices that would attract capital, boost investment and raise Canadian living standards for generations to come.
The story of one of Canada’s most lengthy, deeply unloved, wildly complicated, often necessary pieces of legislation begins simply enough.
In 1917, the country was in its third year of the Great War. The federal government was spending sums of money that would have been scarcely imaginable before the fateful assassination of Archduke Franz Ferdinand. Alongside the Military Service Act, which forced the conscription of soldiers, the Income War Tax Act brought about the conscription of wealth.
By the standards of what followed, that legislation was remarkably slight – no longer than a brochure you might find in a hotel lobby. And as tax law goes, it describes a comparatively simple system imposed on a comparatively simple economy.
The 14-page-long 1917 Income War Tax Act was introduced by the Canadian government as a temporary measure to finance the unprecedented costs of the First World War.Chris Wilson-Smith/The Globe and Mail
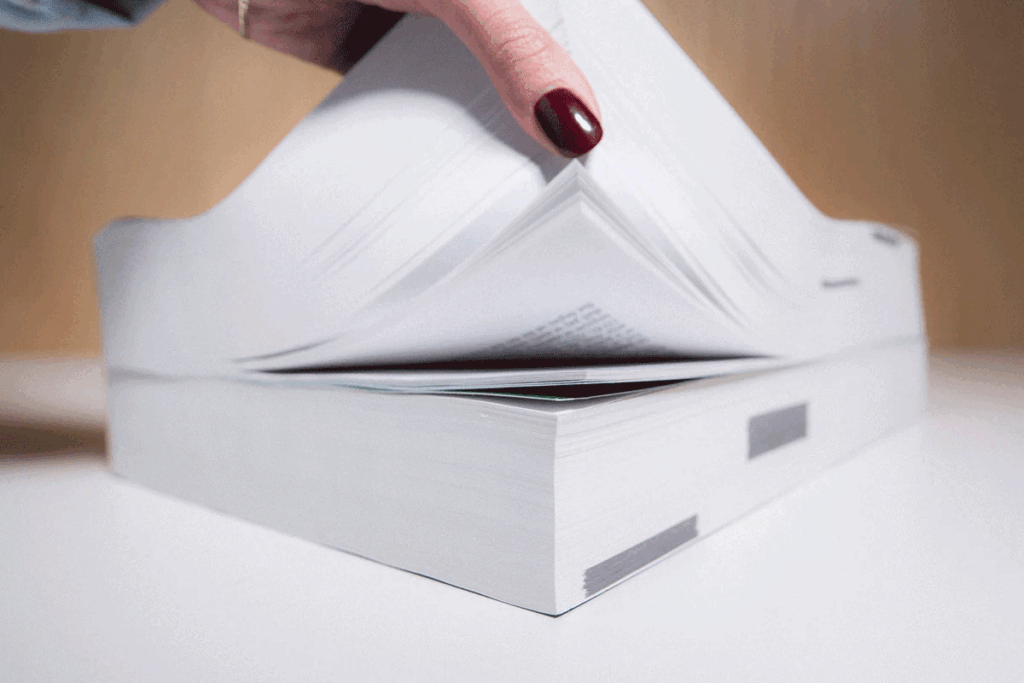
More than a century later, its descendant runs more than one million words – roughly twice the length of War and Peace. The Income Tax Act is a monument to complexity, a dizzying tour through the country’s changing views on the definition of family, the government’s role in the market and the boundary between luxury and necessity. It is an archaeological repository of taxes, provisions and boutique credits accumulated through recessions and booms, demographic shifts, technological change and changing political priorities, heaped upon by layers of exemptions and explanatory notes that might bewilder Tolstoy.
Perhaps most of all, business leaders say, it is the manifestation of a tax system whose complexity imposes billions of dollars in compliance costs alone, while preserving layers of political architecture that are rarely subjected to systematic review.
Steve Suarez, a partner at Canadian legal giant Borden Ladner Gervais, called the current system “a Frankenstein’s monster.”
“Over 50 years, we keep bolting on new pieces, new initiatives, new rules,” Mr. Suarez said. “Nothing ever comes off, just new stuff gets bolted on.”
As a result, he said, companies are spending more and more on lawyers, accountants and internal tax staff simply to comply. Small businesses are left largely adrift, and households are left paying higher bills.
“As a guy with 35 years of experience invested in the current system, I’ve got every incentive to keep the complexity,” he said. “But as a Canadian and as a father, I know we’ve got to do better than this.”
The complicated act of simplification
At the Canadian Tax Foundation’s headquarters in downtown Toronto, a staff member of the organization’s extensive research department has carefully laid out three publications.
Each edition of the Tax Act marks a pivotal moment in Canada’s history – from the strain of a global war to the collapse of trading relations with a close ally – and various trial and tribulations in between.John Kealey/The Globe and Mail
The first is a faded copy of the country’s original income tax statute: The Income War Tax Act of 1917, clocking in at a tight 14 pages. The next was published in 1944 – still modest, but its growth suggesting early sedimentation. The third, the 118th edition of the bilingual Income Tax Act, is just about the size and weight of a breadbox.
Each edition marks a pivotal moment in Canada’s history – a calcification of the country’s social mores, anxieties and priorities.
The two older copies arose amid the emergency strain of global wars, periods that permanently transformed how Ottawa collected revenue. The most recent edition was published in August, 2026, days before a high-stakes round of trade talks collapsed between Canada and the United States.
During his election campaign Mr. Carney made tax simplification part of his platform, and promised a comprehensive “expert review” of corporate taxation. The pledge has yet to materialize.Carlos Osorio/Reuters
As each book was published, politicians were confronting seismic global events. And at each moment, governments might argue they had more immediate problems to solve than the elegance of the tax code. In fact, Mr. Carney made tax simplification part of his platform in the last federal election, promising an expert review of the corporate tax system to improve Canada’s competitiveness and investment climate.
Vows to simplify the tax code are one of Ottawa’s most enduring refrains, echoing across decades of royal commissions, parliamentary committees and think tanks that have launched investigations into its twisted wiring. They often return to strikingly similar diagnoses: broaden the tax base, reduce special preferences and make the system easier and cheaper to administer.
The ruler method
In the mid-2010s, François Vaillancourt, a professor emeritus of economics at the Université de Montréal, was asked by the late tax scholar Richard Bird to collaborate on research into the complexity of Canadian tax law.
He had already spent years studying tax-compliance costs, but complexity itself was newer territory.
The researchers looked around the world for ways to measure a problem that was widely talked about but difficult to show. Eventually, they settled on three indicators: the physical size of the income-tax code, the number of tax expenditures – credits, deductions, exemptions and other special treatments – and the length of the forms, guides and other documents taxpayers had to experience.
But measuring complexity was complicated work. A graduate student working with Mr. Vaillancourt went through historical copies of Canada’s income-tax law and discovered that at one point the book appeared to get considerably shorter. “So I said, ‘Okay, let’s use a ruler,’” Mr. Vaillancourt recalled.
The student went back to the university’s law library, measured the dimensions of the pages and put the results into a spreadsheet, allowing the researchers to compare the physical area occupied by the law over time. It turned out the publisher of that edition had changed the dimensions of the book, making it slimmer and wider. The typography – already a strain on the eyes – was the same. “I don’t think they could have gone to a smaller font.”
Between 1971 and 2014, the researchers found, the physical area occupied by the Income Tax Act and its regulations increased 355 per cent. The number of tax expenditures and the length of taxpayer guides also climbed.
On its own, Mr. Vaillancourt said, the ruler method was “an extremely dumb way to measure complexity.” But the three measurements they used were “highly correlated” over time, he said. None could say precisely how much more complex the system had become, but they pointed in the same direction.
“The bloody three things work together,” he said. “Did it go up by 20 per cent or 24 per cent? Can’t be that precise,” he said. “But it obviously went up.”
In more recent years, software and electronic filing have made it easier at the individual level to navigate that complexity. Mr. Vaillancourt’s research suggests personal compliance costs have fallen even as the underlying tax system has continued to grow more complex.
For small-business owners, however, technological improvements and the promise of artificial intelligence offer much less relief. Expertise is still needed to determine which rules apply, which exemptions are available and how different kinds of income, services and expenses should be treated.
“What’s left are the businesses,” Mr. Vaillancourt said. “And there, complexity is real.”
Serena Thompson is a small-business owner in Markham, Ont. In the twelve years since Ms. Thompson first founded Lighthouse Learning & Development Centre, she has struggled to navigate the complex tax system.Galit Rodan/The Globe and Mail
‘If you’re not an accountant, you’re not an accountant’
Tax complexity can be especially difficult for smaller companies, which face many of the same rules as larger businesses – but are far less likely to have tax specialists or legal departments on staff.
David Pierce, vice-president of government relations at the Canadian Chamber of Commerce, said he hears from business leaders across industries about the time and resources consumed by filing requirements and audits. “The lexicon is different, the substance is the same. It’s too high a tax rate, and it’s too complex to comply with.”
Some anti-avoidance and reporting rules require large numbers of compliant businesses to do more paperwork because government is trying to catch a much smaller number of rule-breakers, he said.
Serena Thompson, founder and executive director of Lighthouse Learning and Development Centre in Markham, Ont., said one of the hardest parts of navigating the tax system as an entrepreneur is not knowing what you don’t know.
Credits, exemptions and different tax treatments might be available, but finding them – and understanding which rules apply – often requires expertise that a small company can’t manage alone.
Ms. Thompson founded Lighthouse 12 years ago after deciding her autistic son was not getting the support he needed in the public school system. The school and therapy centre serves children and young adults with autism, and has grown from six employees to about 20.
For tax purposes, however, Lighthouse is considerably harder to describe: It is a registered private school that can grant high-school credits, an autism therapy centre, a not-for-profit and a registered charity. It employs regulated health professionals, including occupational therapists and speech-language pathologists, and serves families who may use different government support programs to help pay for its services.
Though she initially tried to handle her company’s finances herself, Ms. Thompson eventually sought the help of a tax expert.Galit Rodan/The Globe and Mail
Ms. Thompson, a former police dispatcher with York Regional Police, tried to handle the company’s finances herself in its early days. But it eventually became clear the time and money would be better spent hiring outside help – experts who knew which rules applied, what could be claimed and where mistakes might lead to penalties.
“If you’re not an accountant, you’re not an accountant,” she said.
Even working with outside help can bring its own complexity. Each tax filing season can bring new questions about transactions and expenses that seemed straightforward when they occurred, Ms. Thompson said – but which require her to go back and explain what was spent, why it was spent, and for which part of her multifaceted organization.
In her ideal world, “you keep track of how much money you bring in, and you keep track of how much money you pay out.
“It should really be that simple, but it’s not.”
Complex world, complex code
Canada’s Income Tax Act has grown partly out of convenience, and partly as a reflection of the world growing around it.
Governments increasingly used the tax system to deliver policies that might otherwise have taken the form of direct spending, said Jack Mintz, an economist who chaired then-finance minister Paul Martin’s 1997 Technical Committee on Business Taxation.
Politicians prefer to announce tax cuts to saying they’re spending more money, Mr. Mintz said. But somebody ultimately pays – through higher taxes elsewhere, lower spending or larger deficits pushed onto future taxpayers.
Economist Jack Mintz in 2013. In 1997 Mr. Mintz chaired then-finance minister Paul Martin’s Technical Committee on Business Taxation. Their final report formed the blueprint for corporate tax reform in Canada.Chris Bolin/The Globe and Mail
And when the code was made more permanent following the First World War, it was built for an economy of standalone businesses, domestic production and simple transactions. Even when Ottawa soon introduced a separate federal sales tax levied largely at the manufacturing stage, the economy still fell into relatively neat buckets: some companies made things, wholesalers distributed them and retailers sold them.
“You didn’t have derivatives, you didn’t have all these sorts of complex transactions,” Mr. Mintz said. “It was a very simple society compared to what we have today.”
Over the decades that followed, companies grew larger and more integrated, supply chains stretched across borders, capital markets became more sophisticated and governments increasingly used the tax system to encourage particular kinds of investment.
By the mid-1980s, after years of added investment tax credits, special preferences and measures to snuff out unintended consequences and loopholes, the corporate tax system had become unwieldy.
Tax incentives required officials to make new rulings on what counted as manufacturing, at one point determining that bottling imported perfume still constituted making something. Many companies ended up in tax-loss positions – that is, having enough deductions and credits to wipe out their taxable income – and began looking for ways to transfer those losses to other companies.
“We’ve got to clean the system up,” Mr. Mintz recalled of the thinking inside the federal Department of Finance, where he worked on corporate tax restructuring at the time. “It just – it’s not working.”
Former prime minister Brian Mulroney in December, 1987. That year his Progressive Conservative government sparked widespread outrage when they proposed a 9 per cent GST as part of a larger tax reform effort.Fred Lum/The Globe and Mail
A ‘big bang’
By 1987, the Progressive Conservative government of Brian Mulroney had made replacing the manufacturers’ sales tax a central part of a broader overhaul. Its effort to simplify and modernize Ottawa’s sales tax eventually produced the goods and services tax, still in place more than 35 years later, but not before becoming one of the most complicated political episodes in Canadian history.
The proposed 9-per-cent tax would extend the sales-tax base across much of the growing services economy, replacing the manufacturers’ sales tax with a broader, more visible levy. Basic groceries were to remain untaxed. Instead of taxes on manufacturers being buried in prices – what economists called an invisible tax – they would appear openly on receipts.
The initial introduction of the GST proposal triggered outrage across the country. As the House of Commons finance committee held hearings and consultations, federal finance and tax officials were left working through the consequences of a tax that left basic groceries untaxed but applied to most other goods and services. That meant engineering a structural divide between sustenance and indulgence – groceries and snacks.
Drawing from a mysterious branch of mathematics, bureaucrats determined that anywhere from one to five muffins – or any kind of sweet pastry, for that matter – was a taxable snack. A box of six would be considered a “zero-rated” grocery staple.
A whole mess of complications arose for retailers and restaurants, who warned Ottawa that distinctions like these would turn minimum-wage grocery clerks into tax compliance judges.
After a Senate battle for the ages – culminating in Mr. Mulroney’s unprecedented use of a constitutional provision to appoint eight additional senators – the bill eventually passed, leaving rules that still define how many muffins it takes for them to be considered groceries.
But the upheaval also illustrated how sweeping change can be easier to absorb than constant tinkering, Université de Montréal’s Mr. Vaillancourt said.
“GST at least was implemented as a ‘big bang’ once and now it’s working,” he said. “Everybody had to do something once.”
For decades, various committees and think tanks have launched investigations into simplifying the “Frankenstein’s monster” tax system. Despite the emergence of similar recommendations, widespread reform has yet to be undertaken.John Kealey/The Globe and Mail
‘Is this working’?
In a report published by the C.D. Howe Institute in March, Mr. Mintz and his co-authors called for another big bang – proposing a sweeping overhaul that would lower and simplify personal income taxes, strip preferences from the corporate system and stop trying to achieve so many policy objectives through exceptions to the rules. The paper estimated that complying with Canada’s business tax system costs companies about $14.7-billion a year.
“It’s asymmetric, right?” Mr. Mintz said. “It’s easier to introduce, but it’s harder to take away.”
If history suggests a complete rewrite isn’t soon in the cards – Mr. Carney seems to have shelved his promised expert review – Ottawa should still show more routine introspection, said Ryan Minor, director of tax at CPA Canada.
Every new credit, exemption or other tax measure should begin with a clear objective and, crucially, be more periodically tested against it, he said.
“There’s no difference between giving someone a tax break than it is writing a check,” Mr. Minor said. Governments tend to examine whether direct spending delivers value for money, he said, while tax expenditures can remain in the code without the same scrutiny.
“Is this working?” he said. “If it’s not working, get rid of it or fix it.”
The federal government does not keep an estimate of how much tax complexity costs it. In an e-mailed response, a spokesperson for the Finance Department said it acknowledged that “complexity increases costs for governments and taxpayers,” and can make it harder for people and businesses to understand their obligations and claim benefits.
The department pointed to pre-filled tax returns, streamlined access to the disability tax credit and the elimination of the underused housing tax as recent simplification efforts, and said it would continue looking for opportunities to make the system simpler and more efficient.
Mr. Vaillancourt is skeptical of the word “simplification” to begin with. Calls for a simpler tax system often aren’t really about making the code easier to understand, he said.
“Simplification means ‘I pay less taxes, you pay more taxes.’”
Illustration by D. McFadzean/The Globe and Mail
Tax and Effect: More from The Globe and Mail
Where do my tax dollars go? We’ve created a tool to help answer that question
How Ottawa could cut personal income taxes – without creating a fiscal mess
Q&A: Can Canada’s tax system be reformed? We answered your questions
Opinion: To resist American domination, Canada must fix its failing tax system


More Stories
Before AI can kill us the bubble will burst
Quebec has lost its economic ambition, high-profile business leaders say
Financial-crime regulations governing lawyers require ‘considerable improvements,’ watchdog says